


How Much BTC to Retire: The Exact Math for 2035, 2040 & Beyond
The dream of retiring early through the Financial Independence, Retire Early (FIRE) movement has undergone a radical transformation. For decades, traditional retirement planning revolved around the standard Trinity Study: amass 25 times your annual living expenses in a 60/40 portfolio of index funds and government bonds, then withdraw 4% annually.
However, in an era of persistent fiat currency debasement, escalating global public debt, and eroding bond yields, millions of investors are turning to the hardest asset on Earth: Bitcoin.
Across online financial communities and search engines, queries like how much btc do i need to retire, how much bitcoin to retire in 2035, how much btc to retire reddit, and btc to real calculator have surged to record highs.
Can you retire on 0.5 BTC, 1.0 BTC, or 3.0 BTC? What will Bitcoin be worth in 2035 after the next two halvings, or in 2040 when over 99% of all 21 million coins have been mined? And how does an emerging market currency like the Brazilian Real (BRL) alter the retirement equation?
This definitive guide breaks down the cold, hard mathematical reality of retiring on Bitcoin without taking reckless risks.
1. The Core Retirement Formula: How Much Bitcoin is Enough?
Retirement planning with Bitcoin begins with the same fundamental question as any traditional portfolio: how much cash flow do you need to live comfortably each year?
$$\text{Total Capital Required} = \frac{\text{Annual Living Expenses (USD or BRL)}}{\text{Safe Withdrawal Rate (SWR)}}$$
$$\text{Bitcoin Required} = \frac{\text{Total Capital Required}}{\text{Projected BTC Price at Retirement}}$$
                       ┌──────────────────────────────────────────────┐
                       │           ANNUAL LIVING EXPENSES             │
                       │   e.g. $60,000 / year (or R$ 330,000 / yr)   │
                       └──────────────────────┬───────────────────────┘
                                              │
                        ┌─────────────────────┴─────────────────────┐
                        │                                           │
       ┌────────────────▼─────────────┐           ┌─────────────────▼───────────┐
       │     SAFE WITHDRAWAL RATE     │           │     FUTURE BITCOIN PRICE    │
       │    3.0% - 4.0% per annum     │           │   e.g. $500,000 vs $1,000,000│
       └────────────────┬─────────────┘           └─────────────────┬───────────┘
                        │                                           │
                        └─────────────────────┬─────────────────────┘
                                              ▼
                               ┌──────────────────────────────┐
                               │  TOTAL BTC NEEDED TO RETIRE  │
                               │   e.g. 1.0 to 2.0 BITCOIN    │
                               └──────────────────────────────┘
The SWR Paradox: Why Bitcoin Changes the 4% Rule
The traditional 4% Safe Withdrawal Rate assumes a relatively stable equity/bond portfolio that historically survived a 30-year horizon.
Because Bitcoin experiences brutal 60% to 75% cyclical bear market drawdowns, a rigid 4% withdrawal rate during a bear market could force you to sell your Bitcoin at the absolute bottom (reverse dollar-cost averaging). To retire safely on Bitcoin, professional wealth managers recommend:
1. A Conservative 2.5% to 3.0% SWR on your total Bitcoin stack.
2. The 3-Year Cash Buffer Strategy (Barbell Method): Holding 36 months of living expenses in short-term government bonds or cash, ensuring you never sell a single satoshi during a bear market trough.
Video Breakdown: The Exact Math to Retire on Bitcoin
Watch this analytical deep dive walking through the mathematical models and Monte Carlo simulations for Bitcoin retirement:
2. How Much BTC to Retire in 2035? (The 2-Halving Horizon)
By 2035, Bitcoin will have completed its 5th and 6th halvings (in 2028 and 2032). Block rewards will drop to just 0.78125 BTC per block, resulting in an annual supply inflation rate of less than 0.20% — making Bitcoin drastically scarcer than gold.
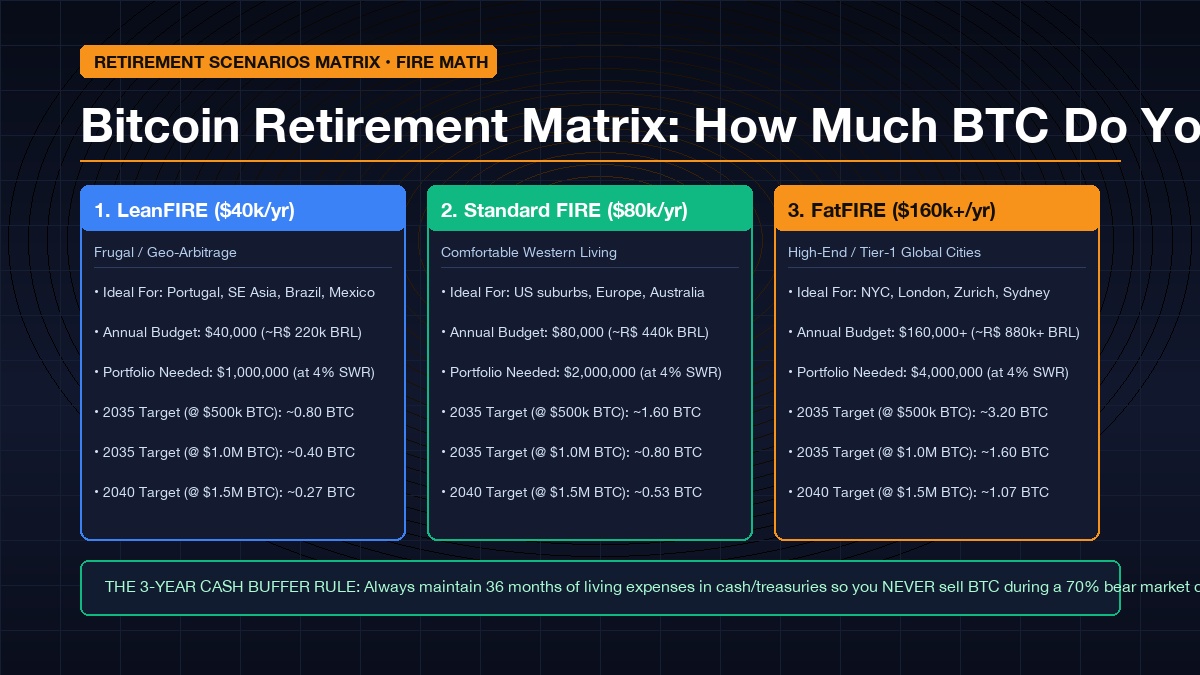
Projected 2035 Bitcoin Price Models:
- Bear / Conservative Case ($350,000 USD): Bitcoin captures roughly 35% of gold’s market cap; institutional adoption slows but holds firm.
- Base / Moderate Case ($750,000 USD): Bitcoin achieves parity with physical gold’s total market cap (~$16 Trillion) as sovereign wealth funds and global pension systems allocate 2% to 5%.
- Bull Case ($1,250,000+ USD): Hyperbitcoinization thesis (Cathie Wood / Ark Invest & Fidelity models), where Bitcoin becomes the premier global settlement tier.
Exact BTC Needed to Retire in 2035 (Table):
| Retirement Lifestyle | Annual Budget (USD) | Capital Needed (at 3.5% SWR) | BTC Needed (@ $350k Bear) | BTC Needed (@ $750k Base) | BTC Needed (@ $1.25M Bull) |
|---|---|---|---|---|---|
| LeanFIRE (Frugal / Expat) | $40,000 / yr | $1,142,000 | 3.26 BTC | 1.52 BTC | 0.91 BTC |
| Standard FIRE (Middle Class) | $80,000 / yr | $2,285,000 | 6.53 BTC | 3.05 BTC | 1.83 BTC |
| FatFIRE (Affluent / Tier-1 City) | $150,000 / yr | $4,285,000 | 12.24 BTC | 5.71 BTC | 3.43 BTC |
Key 2035 Takeaway: In a base-case scenario where Bitcoin reaches $750,000, holding between 1.5 and 3.0 BTC is the mathematical threshold to retire comfortably in most Western nations without working another day.
3. How Much BTC to Retire in 2040? (The Mature Reserve Phase)
By 2040, the world will experience the 7th halving (2036) and 8th halving (2040). At this stage, 99.2% of all 21 million Bitcoins will have been permanently minted. The remaining 0.8% will trickle out over the subsequent 100 years.
In 2040, Bitcoin will no longer be an emerging speculative tech asset; it will be a mature, low-volatility global reserve asset.
Projected 2040 Bitcoin Price Models:
- Conservative Model ($1,000,000 USD): Bitcoin equals gold’s market cap adjusted for modest inflation.
- Base Monetary Model ($2,000,000 USD): Bitcoin demonetizes gold, offshore private banking deposits, and a portion of global sovereign debt reserves ($40T+ market cap).
- Super-Cycle Model ($4,000,000+ USD): Global reserve currency status (Michael Saylor / Hal Finney terminal velocity model).
Exact BTC Needed to Retire in 2040 (Table):
| Retirement Lifestyle | Annual Budget (USD) | Capital Needed (at 3.0% SWR) | BTC Needed (@ $1.0M Cons.) | BTC Needed (@ $2.0M Base) | BTC Needed (@ $4.0M Bull) |
|---|---|---|---|---|---|
| LeanFIRE (Frugal / Geo-Arbitrage) | $50,000 / yr | $1,666,000 | 1.67 BTC | 0.83 BTC | 0.42 BTC |
| Standard FIRE (Comfortable) | $100,000 / yr | $3,333,000 | 3.33 BTC | 1.67 BTC | 0.83 BTC |
| FatFIRE (High-End Global) | $200,000 / yr | $6,666,000 | 6.67 BTC | 3.33 BTC | 1.67 BTC |
Key 2040 Takeaway: By 2040, even 0.5 to 1.0 BTC will provide a substantial, dignified retirement nest egg for individuals practicing geographic arbitrage or moderate living standards.
4. The Reddit FIRE Consensus: What Do Real Bitcoiners Say?
If you browse discussions across r/Bitcoin, r/CryptoCurrency, and r/financialindependence, you will notice distinct schools of thought regarding Bitcoin retirement:
The “1 BTC Club” (The Wholecoiner Goal)
On Reddit, the most celebrated milestone is becoming a Wholecoiner (owning 1.0 full BTC). The prevailing consensus is:
* There are only 21 million Bitcoins, but over 60 million millionaires in the world today.
* Mathematically, less than 0.3% of the global population can ever own 1 full Bitcoin.
* Reddit users frequently argue that 1 BTC will eventually be sufficient to retire in any lower-cost-of-living nation (e.g., Thailand, Portugal, Brazil, Costa Rica).
The “Borrow, Don’t Sell” Trap
A popular philosophy on Reddit is the idea of never selling your Bitcoin, but instead posting it as collateral to borrow fiat currency (living off debt tax-free).
- The Reality Check: While attractive in theory, this strategy destroyed thousands of investors during the 2022 bear market. When Bitcoin dropped from $69k to $15k, centralized lending platforms liquidated borrowers’ collateral or froze withdrawals.
- The Reddit Warning: If you borrow against Bitcoin in retirement, maintain an ultra-conservative Loan-to-Value (LTV) ratio under 15% to 20%, or rely strictly on spot partial sales combined with a multi-year cash reserve.
Video Guide: Bitcoin 2026 Conference Retirement Panel
To see veteran Bitcoin investors and analysts debate the exact timeline and requirements for generational wealth, watch this panel discussion:
5. BTC to Real (BRL) Calculator: The Double-Compounding Advantage
For investors living in or retiring to Brazil, or measuring wealth in Brazilian Reais (BRL), the mathematics of Bitcoin retirement are drastically more advantageous due to currency debasement dynamics:
[Bitcoin Appreciates vs. USD] × [USD Appreciates vs. BRL] = [EXPONENTIAL COMPOUNDING IN REAIS]
Over the last 15 years, the Brazilian Real has steadily depreciated against the US Dollar. When you hold Bitcoin in Brazil, you are protected against domestic inflation and currency devaluation on two compounding fronts.
Cost of Living in Brazil vs. USA/Europe:
In Brazil, a monthly budget of R$ 15,000 to R$ 25,000 BRL ($2,700 to $4,500 USD) provides an upper-middle-class, luxurious lifestyle in prime coastal cities (Florianópolis, Rio de Janeiro, Fortaleza) or upscale interiors (São Paulo countryside) with private healthcare, domestic help, and fine dining.
BTC to Real (BRL) Retirement Simulation Table:
(Assuming an exchange rate of ~R$ 5.50 BRL per USD)
| BTC Held | BTC Price in USD | Cotação em Reais (BRL) | Total Patrimônio em Reais | Renda Mensal Sustentável (4% a.a.) | Estilo de Vida no Brasil |
|---|---|---|---|---|---|
| 0.50 BTC | $200,000 | R$ 1.100.000 / BTC | R$ 550.000 | ~R$ 1.830 / mês | Complemento de aposentadoria básica |
| 1.00 BTC | $500,000 | R$ 2.750.000 / BTC | R$ 2.750.000 | ~R$ 9.160 / mês | Confortável no interior / cidades médias |
| 1.50 BTC | $750,000 | R$ 4.125.000 / BTC | R$ 6.187.500 | ~R$ 20.625 / mês | Classe Alta em capitais brasileiras |
| 2.00 BTC | $1,000,000 | R$ 5.500.000 / BTC | R$ 11.000.000 | ~R$ 36.600 / mês | Independência Financeira Plena (FatFIRE) |
| 3.00 BTC | $1,500,000 | R$ 8.250.000 / BTC | R$ 24.750.000 | ~R$ 82.500 / mês | Riqueza Geracional no Brasil |
How to Calculate Your Retirement in BRL:
- Target Monthly Expenses in BRL: Multiply by 12 to find your annual expenditure (e.g., R$ 20,000/mo × 12 = R$ 240,000/yr).
- Total Capital Needed: Divide by 0.04 (4% rule) ➔ R$ 240,000 ÷ 0.04 = R$ 6,000,000 BRL.
- Convert to Bitcoin: At a future projected price of R$ 3,000,000 per BTC (~$550k USD), you need exactly 2.0 BTC to live like royalty in Brazil for the rest of your life.
6. How to Build Your Bitcoin Retirement Strategy (Step-by-Step)
If your goal is retiring on Bitcoin, follow these 4 non-negotiable rules:
- Adopt Systematic Dollar-Cost Averaging (DCA): Do not attempt to time market cycle tops and bottoms. Set up automated weekly or monthly purchases through low-fee brokers to build your stack steadily.
- Practice Pure Cold Storage: Never leave your retirement stack on an exchange. Secure your coins using an open-source hardware wallet (such as Blockstream Jade, Coldcard, or Trezor) stamped into a stainless steel seed backup.
- Build a 3-Year Cash Runway Before Retiring: When you decide to pull the trigger on retirement, accumulate 36 months of living expenses in high-yield cash, Treasury bills, or Brazilian Tesouro Selic. This ensures you never have to liquidate BTC during a severe cyclical drawdown.
- Plan for Taxes: In Brazil and the US, tax rates on long-term capital gains vary based on monthly sales thresholds and brackets. Structure your annual withdrawals to maximize legal tax exemptions (e.g., Brazilian R$ 35,000/month exemption on foreign/crypto sales when applicable).
Frequently Asked Questions (FAQ)
How many Bitcoins do you need to retire comfortably today?
In 2026, with Bitcoin trading between $80,000 and $100,000 USD, retiring today on Bitcoin alone requires between 15 and 25 BTC to generate a comfortable Western income of $60,000 to $100,000 annually under a safe 4% withdrawal rate. However, for future retirement horizons (2035 and 2040), that requirement shrinks to between 0.5 and 2.5 BTC as price models account for future halving supply shocks.
Can I retire on 1 Bitcoin?
In the future (2032–2040), yes. If Bitcoin reaches $1,000,000 USD per coin, a 3% safe withdrawal rate yields $30,000 USD per year. In high-cost cities like New York or London, that represents LeanFIRE. However, in low-tax, low-cost regions like Portugal, Thailand, Mexico, or Brazil, $30,000 USD (~R$ 165,000 BRL) provides a very comfortable, upper-middle-class retirement.
What is the biggest risk of retiring on Bitcoin?
The primary risk is sequence of returns risk driven by Bitcoin’s 4-year cycle volatility. If you retire right before a 70% bear market and are forced to sell Bitcoin to pay for groceries and rent, you rapidly deplete your stack. This is why maintaining a 3-year fiat cash reserve is mandatory for any Bitcoin retirement strategy.
Will Bitcoin ever stop growing?
As Bitcoin reaches multi-trillion-dollar market caps comparable to global real estate and sovereign bonds, its annual percentage gains will naturally slow down, transitioning from a hyper-growth speculative asset into a stable, inflation-resistant store of value.
ThreeDolar Retirement & Wealth Tools
Model your path to financial freedom with our fundamental calculators and rankings:
I started investing in 2014, my first stock was ABEV3 (R$50). I’ve worked with forex, futures, crypto, and derivatives. Here, I share ideas in a relaxed way.